Household finance
A record bet on stocks. AI is carrying the rally
Household portfolios are more exposed to equities than at the peaks of 2000 and 2007. This time, a narrow group of AI winners is doing the heavy lifting.
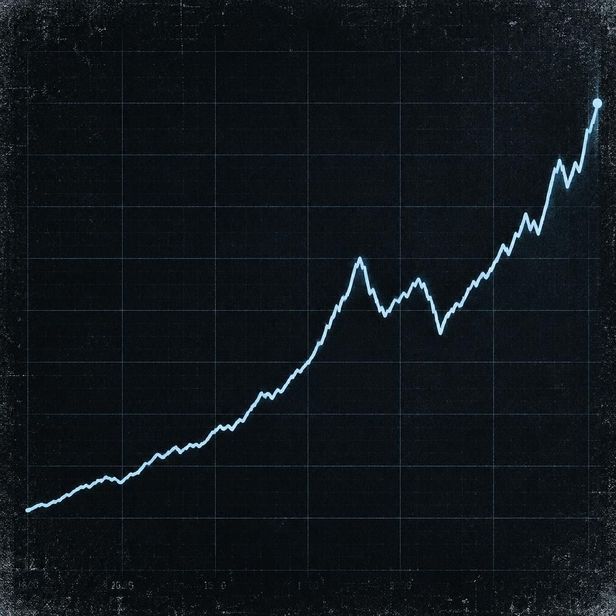
American households have never had so much riding on the stock market. Equities accounted for a record 48.2% of their financial assets in the second quarter of 2026. The Federal Reserve measure captures both direct ownership and holdings through funds and retirement plans. Nearly half of every dollar in financial assets is tied to stocks. Real estate is outside the calculation.
Two memorable peaks over the past 30 years were considerably lower. Stocks reached 38.7% of household financial assets in the first quarter of 2000; from March that year to October 2002, the Nasdaq lost about 78%. The share stood at 33.5% in the second quarter of 2007. Later, between October 2007 and March 2009, the S&P 500 plunged nearly 57% in 17 months. Today’s allocation exceeds those earlier levels by 9.5 and 14.7 percentage points, respectively. The bet has grown substantially.
Fifteen years have taught investors a reassuring routine: someone buys the dip, the index recovers, and the patient passive investor gets another record high. Arithmetic reinforces the lesson. Rising stocks take up more of a portfolio even without fresh purchases. Unless investors rebalance, yesterday’s gains leave their savings increasingly exposed to whatever happens next. After enough successful years, that growing dependence starts to feel like the natural way to hold money.
Yet the rally is leaving a large part of the market behind. Reuters reported on October 12 that the S&P 500 had gained about 14% this year, while its median stock was up only around 4%. More than 200 constituents—over four in ten—were down. A handful of chipmakers and other beneficiaries of the AI race accounted for much of the index’s advance.
“More than 4 in 10 stocks in the index are lower in 2026” — Reuters, October 12
The index can keep that gap out of sight for a long time. Because the S&P 500 weights companies by market capitalization, a few giants can lift the benchmark while hundreds of other stocks go nowhere or fall. An index-fund investor really does own stakes in 500 companies. But the number of independent forces driving those returns can be much smaller, especially when the biggest winners depend on the same investment boom.
Some of the stock-market gains within the AI trade have also shifted in 2026, from infrastructure buyers to their suppliers. Hyperscalers are spending hundreds of billions of dollars, while Micron, AMD and suppliers of storage, equipment and power infrastructure collect the orders. As we explored in our look at the economics of the AI buildout, an accelerator sale brings the supplier revenue straight away. The buyer still has to earn a return on the computing capacity it has paid for. At this stage of the race, selling the equipment is often a more comfortable position than having to make it pay.
That gives very different businesses a shared vulnerability: the continuation of enormous infrastructure budgets. Chips, memory, power systems and cooling span several industries, but a substantial share of their new orders comes from the same buildout. A modest downward revision to its expected pace can damage the outlook for several groups of market leaders at once. Spending can keep rising and still disappoint. It only has to grow more slowly than share prices already assume.
For the third time in 30 years, unusually heavy household exposure to stocks sits alongside deep confidence in further gains. This time, much of the market’s success depends on the AI race. Savers are making two bets at once: that the stock market will hold up, and that the infrastructure boom will justify the valuations of its winners. AI may well transform the economy. The internet did. The Nasdaq crashed anyway.
Imagerly.Ai · No. 28 · October 2026